Reports
Press coverage and detailed reports on unfolding events
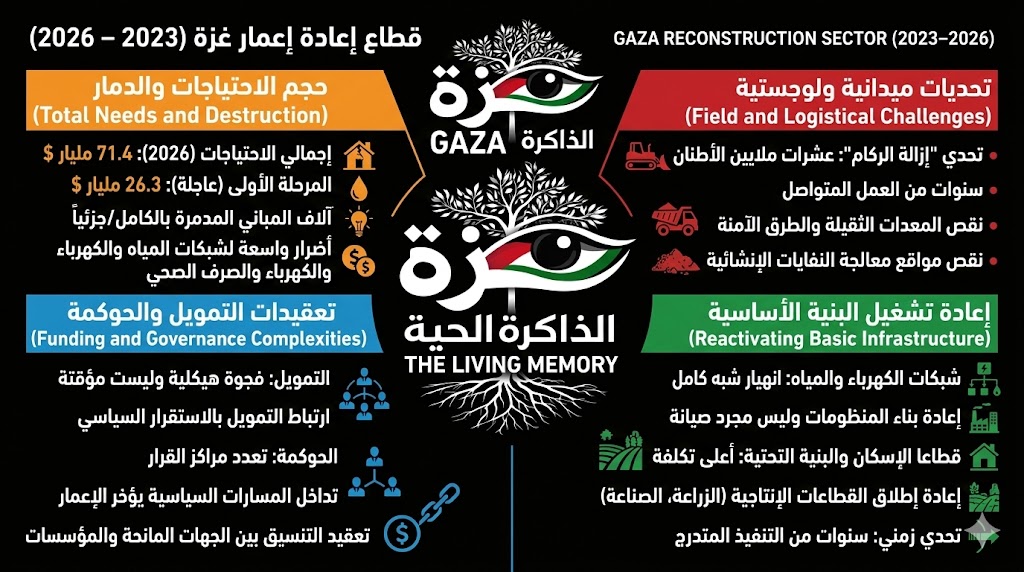
Gaza Reconstruction.. Between Infrastructure Rubble, Financing Complexities, and Governance Challenges Amid Political Overlaps (2023–2026)
Since October 7, 2023, the Gaza Strip has entered an unprecedented phase of destruction in its modern history. The impact has not been limited to residential or service infrastructure but has extended to the very foundations upon which any viable economy depends. As the scale of devastation expanded, the concept of “reconstruction” shifted away from its traditional meaning toward the near-total re-establishment of a devastated urban system in terms of infrastructure, economy, services, and governance simultaneously. According to the joint assessment issued by the United Nations, the European Union, and the World Bank in 2026, Gaza’s recovery and reconstruction needs are estimated at approximately $71.4 billion over the coming years, of which around $26.3 billion is required urgently in the first phase to restore minimum essential services and rehabilitate critical infrastructure. These figures illustrate that the scale of destruction has surpassed the capacity of any comparable reconstruction effort in the region, both in terms of cost, time, and institutional complexity. On the ground, Gaza after the war appears to have lost its basic urban structure. Thousands of residential buildings have been fully or partially destroyed, while water, electricity, and sewage networks have suffered widespread damage, leaving large areas of the Strip effectively non-functional. United Nations estimates indicate that hundreds of thousands of housing units have been destroyed or damaged, while a significant proportion of hospitals and schools have gone out of service due to direct destruction or the collapse of essential operational supplies. This level of collapse means that reconstruction does not begin with rebuilding, but with a “debris removal” phase that is itself a massive engineering and logistical challenge. The enormous quantities of rubble, estimated at tens of millions of tons, require years of continuous work and an operational infrastructure that is currently unavailable, including heavy machinery, safe transport routes, and designated waste processing sites. At the same time, financing emerges as one of the most complex obstacles. Even when large international estimates exist for reconstruction needs, the actual mobilization of funds depends on political, administrative, and international conditionality factors. Previous experiences in similar conflict zones suggest that funding is rarely delivered in a single, comprehensive package but rather in phased and fragmented tranches linked to political stability, oversight mechanisms, and transparency guarantees. This creates a structural—not temporary—financing gap in the early years of reconstruction. In parallel, governance represents one of the most sensitive issues in the reconstruction process. Managing a project of this scale requires a clear executive framework, while the current reality reflects multiple overlapping actors: the Palestinian Authority in Ramallah, United Nations agencies, international donors, and existing administrative structures within Gaza itself. This multiplicity of decision-making centers does not only create administrative complexity but also affects implementation speed, project distribution, and financial and technical oversight mechanisms. In the absence of a unified reconstruction authority in the early stages, coordination among these actors becomes crucial. However, it also becomes a potential source of delay, especially in large-scale projects that require centralized decision-making and long-term institutional stability. At the infrastructure level, the challenge goes beyond rebuilding structures to the restoration of entire systems that have largely collapsed. Electricity networks, once dependent on external supply and limited generators, have suffered widespread disruption. Water and sewage treatment facilities have been severely damaged, making their restoration dependent on rebuilding rather than repairing existing systems. Road networks, which serve as the backbone of economic and humanitarian mobility, have also sustained extensive damage, affecting transportation of goods, services, and aid. Economically, reconstruction cannot be separated from the restoration of the economic cycle itself. Gaza’s local market has lost both its productive and consumption capacity, meaning that recovery requires simultaneous reactivation of key sectors such as agriculture, industry, trade, and services. However, this process depends on the availability of raw materials, the stability of supply chains, and the ability to move goods—factors that remain tied to the broader political and security environment. International estimates indicate that housing and infrastructure sectors account for the largest share of reconstruction costs, followed by essential services. This reflects the priorities of the initial phase, which focuses on restoring minimum living conditions before transitioning to long-term development projects. Behind this entire process lies the time factor, which is as critical as financing. Even if financial resources become available, reconstruction of this magnitude requires a long, phased timeline beginning with debris removal, followed by infrastructure rehabilitation, housing reconstruction, and finally gradual economic recovery. Across all stages, political and administrative stability remains the most sensitive variable. Any disruption at this level directly affects the pace of reconstruction and can push projects back to earlier phases of delay. In conclusion, Gaza’s reconstruction after 2023 is not a conventional engineering project. It represents a comprehensive rebuilding of an entire system of life, where engineering, economics, politics, and governance intersect. This makes it one of the most complex reconstruction challenges in modern history—not only because of the scale of destruction, but because of the nature of the environment in which reconstruction must take place, the multiplicity of actors involved, and the long time horizon required for recovery..
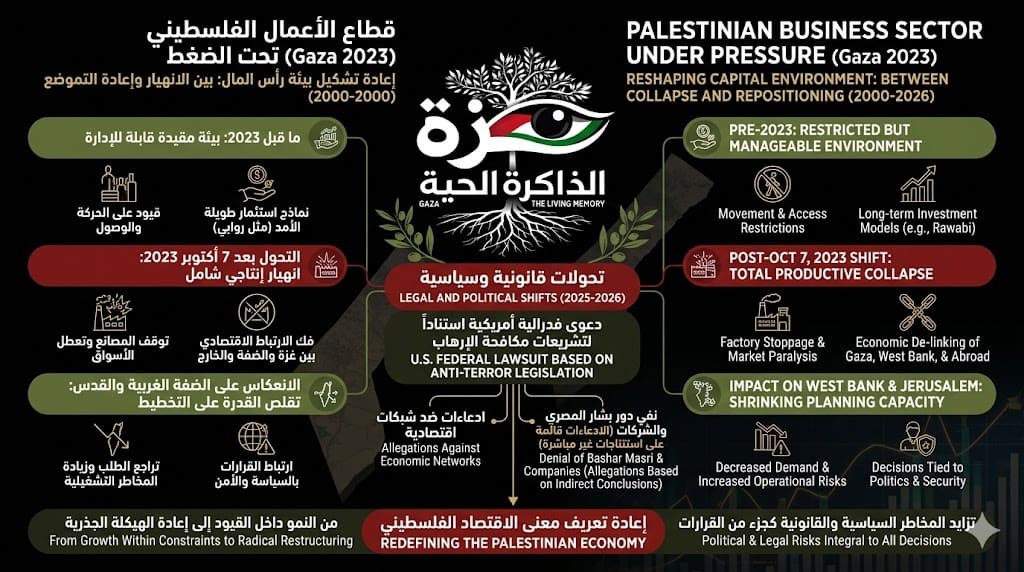
The Palestinian Business Sector Under Pressure.. Gaza 2023 and the Reshaping of Capital Between Collapse and Strategic Repositioning (2000–2026)
Since October 7, 2023, the Palestinian economy—whether in the Gaza Strip or in its extensions in the West Bank and Jerusalem—has no longer operated within a normal trajectory that can be measured through conventional indicators of growth or contraction. What followed this date was not merely an economic shock linked to war, but a structural transformation in the environment in which Palestinian capital operates, whether at the level of companies, investors, or major projects. Gaza, which before the war represented a relatively limited yet somewhat resilient economy in its core sectors, has entered a phase of full-scale productive collapse. With the suspension of the internal economic cycle, not only factories and markets stopped functioning, but also the invisible networks connecting the Palestinian economy were disrupted—supply chains, financial transfers, trade flows, and employment relations between Gaza, the West Bank, and abroad. Before 2023, the Palestinian private sector operated within a constrained yet manageable environment: restrictions on movement, limited access to crossings, export difficulties, and unequal access to markets. Despite these constraints, this environment still allowed for long-term investment models in real estate, services, and infrastructure, along with attempts to build a local economy driven by private initiatives under conditions of incomplete statehood. However, the war on Gaza completely redefined this equation. With the halt of economic activity in the Strip, the Palestinian economy did not merely lose a geographic market; it lost a functional component of its internal structure, particularly in consumption, production, and the monetary cycle that had also supported sectors in the West Bank. This disruption had a direct impact on the investment climate in the West Bank and Jerusalem, where companies began facing not only declining demand but also increased operational risks and reduced capacity for long-term planning. Over time, investment decisions became increasingly tied to political, security, and financial factors beyond the market itself. Within this context, major investment projects led by Palestinian businessmen emerged over the past two decades in an attempt to promote alternative development models. Among them is Bashar Masri, whose name has been associated with large-scale urban development projects, most notably the city of Rawabi, in addition to investments in various sectors in the West Bank and earlier initiatives linked to economic development models connected to the Gaza Strip. Although these projects are economic in nature, they have always operated within an unstable environment, where investment cannot be separated from political geography, nor economic growth from restrictions on movement, infrastructure, and access to resources. Over time, such projects became part of a broader attempt to build a Palestinian economic model based on private initiative under conditions of incomplete sovereignty. After 2023, with the large-scale collapse in Gaza, this equation entered a more complex phase. The disappearance of Gaza from the active economic cycle did not only result in the loss of a consumer and productive market, but also led to a broader restructuring of risks surrounding the Palestinian economy as a whole, including financing risks, expansion risks, and legal and institutional stability risks for major projects. In this context, legal developments emerged in the international arena related to the war on Gaza. Among them is a civil lawsuit filed in a U.S. federal court in 2025 and 2026 by hundreds of plaintiffs representing families of victims of the October 7, 2023 events, based on provisions of U.S. anti-terrorism legislation. The lawsuit included parties and economic networks allegedly connected to operational environments in the Gaza Strip, including the name of businessman Bashar Masri, within claims concerning the role of certain infrastructure or economic projects in the broader environment in which the events took place. In response, Masri and the companies associated with him categorically deny these allegations, affirming that all investments were purely developmental in nature and aimed at creating jobs and strengthening the local economy, with no connection to any military or security activity. The defense team in this case has moved to dismiss the lawsuit, arguing that it is based on indirect assumptions and that attributing liability to development projects in conflict environments represents an unprecedented expansion in the concept of legal responsibility. What distinguishes such cases is not only their legal content, but also the context in which they emerge, as the Palestinian economic environment has increasingly become part of a more stringent international legal field, where financial compliance considerations, geopolitical risk, and interpretations of the relationship between investment and political context intersect. At the same time, the Palestinian private sector is operating within a broader network of structural constraints, including limited market access, disrupted supply chains, and heavy dependence on an unstable political environment, making any economic expansion conditional on external factors beyond market logic. With the continuation of the war on Gaza since 2023, the discussion is no longer limited to a local economic crisis, but rather extends to a comprehensive restructuring of the role of the Palestinian economy, as production capacity declines, markets shrink, and the gap between economic potential and actual reality deepens. In conclusion, the Palestinian private sector today stands at a fundamentally different stage from the past two decades. The challenge is no longer growth within constraints, but rather redefining the very meaning of “economy” within an environment where the rules of operation and investment are being reshaped dramatically, and where political and legal risks have become an integral part of every economic decision..
.jpeg)
The Agricultural Sector in Gaza: From a Besieged Food Basket to Devastated Farmland — The Story of Agricultural Collapse Since October 7, 2023
When the war erupted in the Gaza Strip on October 7, 2023, agricultural land was far more than green fields producing food. Agriculture represented one of the last pillars of economic and social resilience in a territory that had endured more than seventeen years of blockade. For decades, farming provided food, employment, and income for tens of thousands of Palestinian families, contributing nearly 10 percent of Gaza’s economy. More than 560,000 people depended directly or indirectly on agriculture, livestock, and fishing for their livelihoods. What followed during the war transformed this vital sector from a source of life into one of the most devastated sectors in Gaza’s modern history. Before the war, Gaza contained approximately 15,053 hectares of agricultural land, equivalent to more than 150 million square meters devoted to field crops, vegetables, fruit trees, orchards, and greenhouse cultivation. The governorates of North Gaza, Khan Younis, and Rafah formed the agricultural heartland of the territory, hosting olive groves, citrus orchards, almond trees, vegetable farms, strawberry fields, and thousands of dunums planted with wheat, barley, and seasonal crops. These same areas later became major military operation zones, where farmland was subjected to bombardment, bulldozing, burning, and widespread destruction. During the first months of the war, satellite imagery began revealing the scale of the catastrophe. By February 2024, approximately 42.6 percent of Gaza’s agricultural land had already sustained direct damage. Just three months later, the figure rose to 57.3 percent. By September 2024, the proportion of damaged agricultural land reached 67.6 percent of all cultivated areas in Gaza, representing more than 10,000 hectares that had been destroyed, bulldozed, or severely damaged. Satellite-based assessments further showed that 71.2 percent of orchards and tree-covered areas had been affected, alongside damage to 67.1 percent of field crops and 58.5 percent of vegetable-growing areas. As the conflict continued throughout 2025, the destruction deepened dramatically. According to the latest joint assessment conducted by the Food and Agriculture Organization of the United Nations (FAO) and the United Nations Satellite Centre (UNOSAT), more than 80 percent of Gaza’s agricultural land had sustained direct damage by April 2025. This amounted to 12,537 hectares out of the territory’s total 15,053 hectares of agricultural land. Furthermore, 77.8 percent of farmland had become inaccessible due to military operations, buffer zones, or security risks, leaving only 688 hectares available for cultivation—just 4.6 percent of Gaza’s agricultural area. The crisis did not stop there. By July 2025, new United Nations assessments indicated that more than 86 percent of agricultural land had suffered damage, while 98.5 percent of Gaza’s farmland was either damaged, inaccessible, or both. In practical terms, only 232 hectares remained available and suitable for cultivation out of more than 15,000 hectares that had been farmed before the war. This meant that merely 1.5 percent of Gaza’s agricultural land remained operational. One of the most visible aspects of the destruction was the extensive bulldozing of farmland. Satellite imagery documented the removal of thousands of dunums of orchards and agricultural fields, particularly in North Gaza, eastern Gaza City, eastern Khan Younis, and Rafah. Palestinian estimates suggest that more than 178,000 dunums of agricultural land suffered varying degrees of destruction, bulldozing, or severe damage, representing over 80 percent of Gaza’s total agricultural area. Vegetable cultivation alone experienced a dramatic collapse, with cultivated areas shrinking from approximately 93,000 dunums before the war to only about 4,000 dunums during certain phases of the conflict. Agricultural infrastructure suffered equally devastating losses. FAO data indicate that 71.2 percent of greenhouses had been damaged or destroyed by spring 2025, with the figure rising to nearly 80 percent later that year. In some areas, particularly Gaza Governorate and North Gaza, greenhouses virtually disappeared from the agricultural landscape. Agricultural water wells, which serve as the lifeline of farming in Gaza, also sustained extensive damage. By April 2025, approximately 82.8 percent of agricultural wells had been damaged or completely destroyed, compared with 67.7 percent at the end of 2024. This destruction deprived thousands of farmers of the ability to irrigate their fields, even in areas that had escaped direct bulldozing. The livestock sector experienced a similarly catastrophic decline. Bombardment, shortages of feed, limited water supplies, and the lack of veterinary medicines led to the death of large numbers of animals. International reports described a near-total collapse of the poultry sector, while cattle, sheep, and goat farms suffered severe losses. Palestinian assessments indicate that hundreds of livestock and poultry farms were either destroyed or forced out of operation during the war. By 2026, the crisis had evolved from an agricultural disaster into a full-scale food security emergency. Land that once produced vegetables, fruits, grains, and other essential food products had largely become inaccessible, destroyed, or unsuitable for cultivation. Agricultural infrastructure built over decades had been devastated. Various assessments showed that less than 5 percent of Gaza’s farmland remained available for cultivation during parts of 2025, while later evaluations found that only 1.5 percent of agricultural land was both intact and accessible for productive use. The losses suffered by Gaza’s agricultural sector cannot be measured solely in terms of bulldozed land, uprooted trees, or destroyed greenhouses. They must also be measured by the food production capacity that has been lost. Every dunum destroyed once produced food. Every damaged well once irrigated fields. Every uprooted tree represented years of investment and cultivation. Today, more than two and a half years into the war, Gaza’s agricultural sector stands as one of the most severely affected sectors of the economy and as a symbol of one of the largest agricultural disasters witnessed in the modern Middle East. Rehabilitating farmland, rebuilding irrigation systems, restoring greenhouses, and reviving agricultural production will require years of sustained effort and billions of dollars before even a fraction of Gaza’s former productive capacity can be recovered..
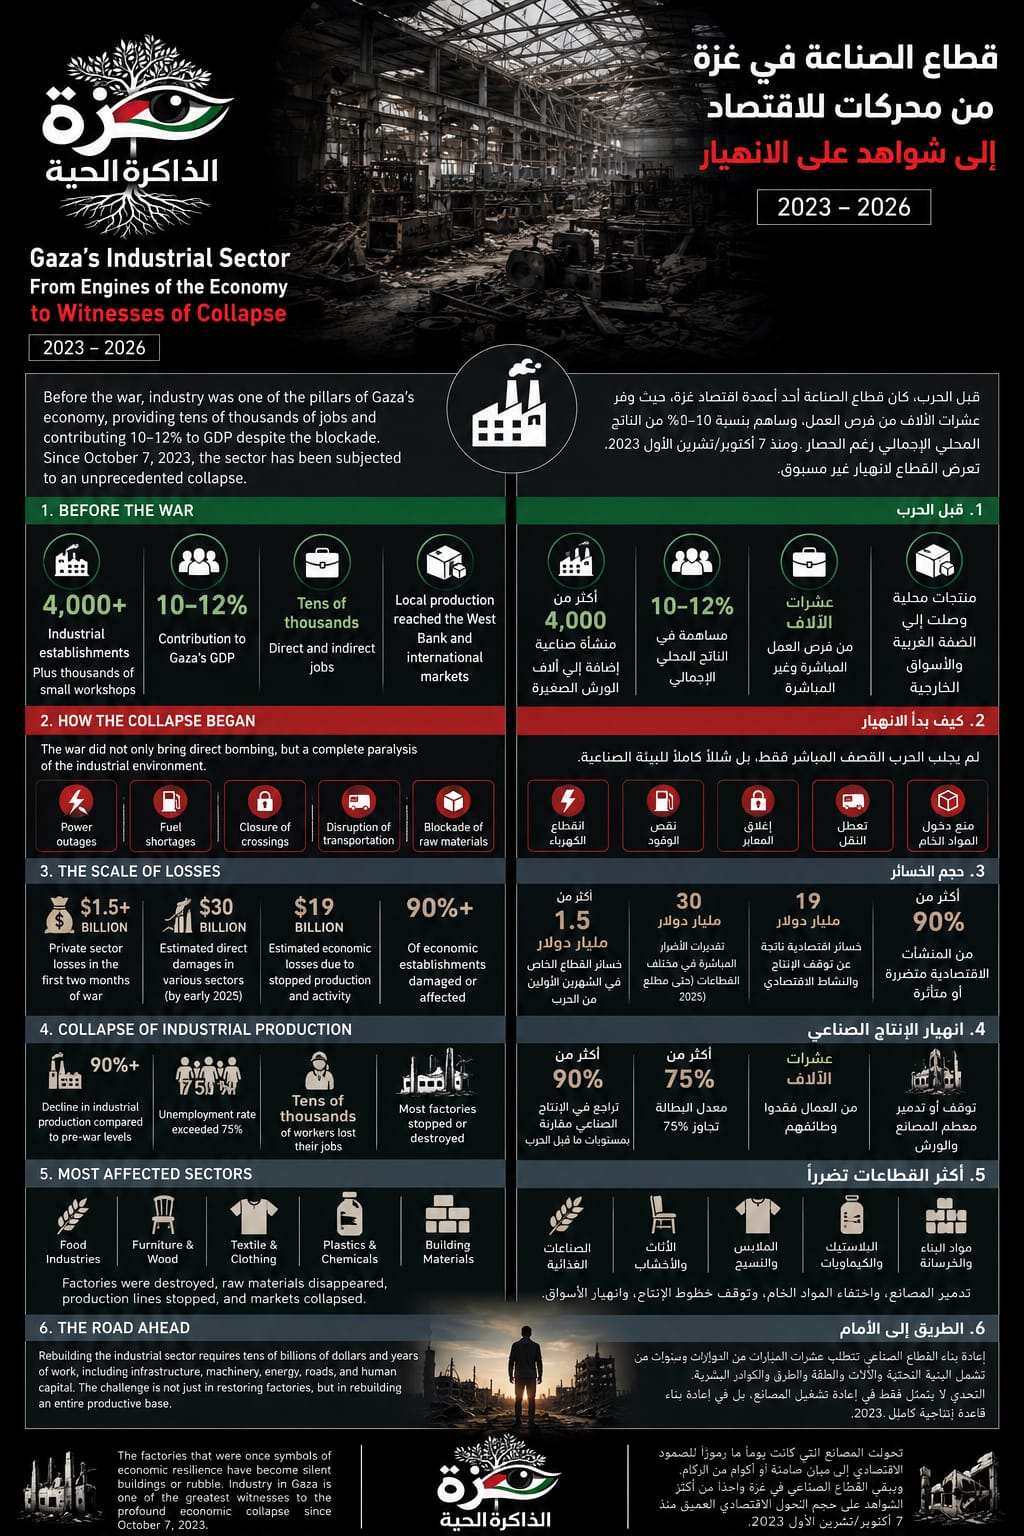
The Industrial Sector in Gaza: How Factories Turned from Engines of the Economy into Symbols of Collapse (2023–2026)
On the morning of October 7, 2023, Gaza’s industrial sector was operating under difficult conditions imposed by years of blockade. Yet despite these challenges, it maintained a minimum level of production and economic activity. Hundreds of factories and thousands of workshops produced food, furniture, clothing, plastic products, metal goods, and construction materials, serving as one of the territory’s most important sources of employment and income. Before the war, Gaza was home to more than 4,000 industrial establishments of varying sizes, in addition to thousands of small workshops and craft businesses. Industry contributed approximately 10–12 percent of Gaza’s gross domestic product and provided tens of thousands of direct and indirect jobs. Despite restrictions on imports and exports, some factories were able to reach markets in the West Bank and abroad, while food processing, construction-related industries, and textile manufacturing formed key pillars of the local economy. The war that began in October 2023, however, struck not only residential areas and public infrastructure but also the heart of Gaza’s productive economy. Within days, factories began shutting down one after another. The reasons extended far beyond direct bombardment. Electricity supplies collapsed, fuel reserves were depleted, transportation networks were disrupted, border crossings were closed, and the flow of raw materials essential to industrial production was cut off. During the first weeks of the conflict, hundreds of factories found themselves unable to continue operating. Production lines came to a halt, generators stopped due to fuel shortages, and warehouses filled with goods that could neither be sold nor transported. At the same time, losses across the private sector mounted rapidly. Preliminary estimates indicated that private-sector losses exceeded $1.5 billion during the first two months alone, with industry accounting for a significant share because of the high value of industrial assets, machinery, equipment, warehouses, and production facilities. As the war expanded throughout 2024, the industrial sector entered a new phase of collapse. The issue was no longer merely the suspension of production; it became the physical destruction of industrial infrastructure itself. Dozens of factories were either directly hit or severely damaged, while entire industrial zones were transformed into devastated landscapes. Aerial imagery documented the disappearance of industrial facilities that had once served as major production centers in Gaza City, Khan Younis, and Rafah. According to joint assessments by the United Nations, the World Bank, and the European Union, the trade and industrial sectors became among the most heavily affected economic sectors after housing. By early 2025, physical damage across all sectors was estimated at approximately $30 billion, while economic losses resulting from halted production and business activity reached an additional $19 billion. Within the factories themselves, losses extended far beyond damaged buildings. Entire production lines were destroyed or rendered inoperable. Machinery acquired over many years ceased functioning. Warehouses containing raw materials and finished products were burned, damaged, or destroyed. Thousands of industrial businesses also lost operational records, transportation assets, distribution networks, and critical business infrastructure. The food manufacturing industry, one of Gaza’s most important productive sectors, suffered particularly severe damage. Dozens of food-processing facilities were destroyed or forced to suspend operations. Dairy plants, juice factories, canning facilities, and bakeries faced immense difficulties in obtaining raw materials and energy supplies. As a result, local food production declined sharply, increasing dependence on humanitarian assistance. The furniture and woodworking sector, once one of Gaza’s best-known industries, experienced a devastating setback due to the destruction of factories and workshops and the inability to import necessary raw materials. The textile and garment industry, which had employed thousands of workers before the war, also came to a near-complete standstill, with the vast majority of factories ceasing operations. Plastic and chemical industries faced similar challenges. These sectors rely heavily on imported raw materials, and once supplies stopped entering Gaza, production lines became idle even in facilities that had escaped direct damage. Factories producing construction materials, concrete products, stone, and marble were likewise severely affected by both physical destruction and shortages of essential inputs. By the end of 2024, international institutions were describing Gaza’s economic collapse as one of the most severe in modern history. Gaza’s economy contracted by more than 80 percent, among the sharpest economic declines recorded globally in recent decades. Economic assessments suggested that industrial output had fallen by more than 90 percent compared to pre-war levels, effectively eliminating most of the territory’s productive capacity. The crisis also had a profound impact on employment. Tens of thousands of industrial workers lost their jobs as factories and workshops closed. Unemployment became widespread, affecting nearly every family in some form. World Bank estimates indicated that unemployment in Gaza exceeded 75 percent, while jobs directly linked to manufacturing and industrial production virtually disappeared. As the conflict continued through 2025 and into 2026, the challenge shifted from restarting damaged factories to rebuilding an entire productive base. Many industrial facilities no longer existed, while others required comprehensive reconstruction involving buildings, machinery, electricity networks, water systems, and transportation infrastructure. Recent economic estimates suggest that more than 90 percent of Gaza’s economic establishments suffered destruction or varying degrees of damage. This figure includes thousands of industrial enterprises that once formed the backbone of local production. Reconstruction of Gaza’s productive economy is expected to require tens of billions of dollars and many years of sustained investment, even if hostilities cease completely. Today, more than two and a half years after the outbreak of war, the losses suffered by Gaza’s industrial sector can no longer be measured solely by the number of factories destroyed or the value of machinery rendered unusable. The territory has lost a substantial portion of its ability to manufacture food, medicine, clothing, construction materials, and other essential goods. Alongside this, it has lost thousands of skilled workers, technicians, and craftsmen whose expertise had accumulated over decades. Factories that once symbolized economic resilience have become silent structures or piles of rubble. As the war continues, the industrial sector remains one of the hardest-hit areas of Gaza’s economy and stands as a powerful testament to the profound economic transformation that has unfolded since October 7, 2023—a transformation that will be neither easy nor quick to reverse, even after the guns fall silent..
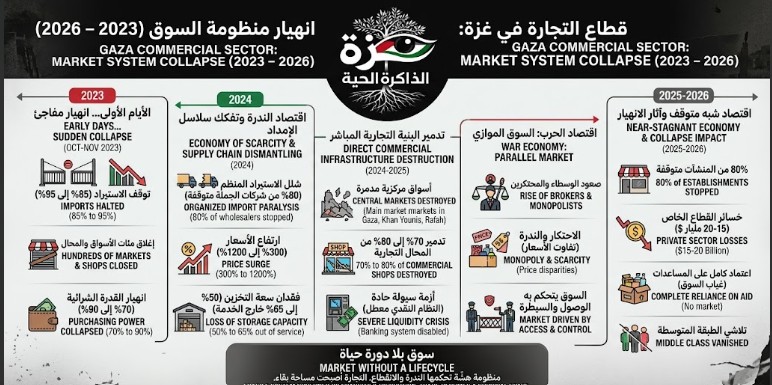
The Commercial Sector in Gaza: The Collapse of the Market System Under War (2023–2026)
Gaza, the Living Memory – When War Closes the Market's Doors The war that erupted on October 7, 2023, was not merely a military confrontation spanning the geography of the Gaza Strip; rather, it constituted a defining moment that reshaped the economy from its roots—particularly the commercial sector, which serves as the backbone of daily life. In the early days, indicators of collapse began to surface rapidly with the closure of crossings, the halting of imports, and a decline in the flow of essential commodities, alongside widespread disruption in local markets. Over time, discussions shifted from an economic recession to a gradual dismantling of the entire market system. Traditional rules of trade vanished, and the economy transformed into an exceptional state managed by scarcity and necessity. First: The Early Days… A Sudden Market Collapse (October – November 2023) In the opening weeks of the war, Gaza's commercial sector suffered a complex shock that struck all its components simultaneously. Near-Total Cessation of Imports: With crossings effectively closed or minimized to the bare lowest threshold, the entry of essential commercial goods ground to a near-total halt. Foodstuffs, fuel, construction materials, and medical supplies were entering in limited quantities that failed to cover the bare minimum of daily needs. Commercial import activity dropped by an estimated 85% to 95%. Markets Under Shock: Hundreds of popular markets closed their doors, and thousands of small and medium-sized retail shops ceased operations due to destruction, displacement, or supply chain disruptions. Nevertheless, features of a new makeshift market emerged, relying on remaining inventories or sporadically delivered items. Collapse of Internal Demand: Thousands of families lost their sources of income within a short period, and purchasing power plummeted sharply, with drops estimated between 70% and 90%. Following this collapse, the market transformed into a space focused strictly on survival essentials. Second: 2024… The Economy of Scarcity and the Dismantling of Supply Chains As the war entered its second year, the commercial economy transitioned from a state of shock to a continuous, structural collapse. Paralysis of Organized Importation: Organized commercial importing virtually stopped, leaving the market reliant on limited humanitarian aid, old inventories, and small quantities entering irregularly. This situation led to the breakdown of the role of wholesale and distribution companies, which had previously formed the backbone of the market. Estimates indicate that more than 80% of distribution and wholesale companies ceased operations completely or partially. Unprecedented Surge in Prices: Essential goods experienced sharp and recurring price hikes, reaching between 300% and 1200% at certain intervals compared to pre-war levels. Furthermore, some commodities vanished entirely during specific periods, exacerbating the severity of the scarcity. Collapse of Warehousing and Supply Chains: Warehouses faced destruction or disruption, alongside a total loss of storage capacity due to electricity and fuel blackouts. Field estimates indicate that between 50% and 65% of storage capacities rendered out of service. Third: Destruction of the Commercial Infrastructure (2024–2025) With the continuation of military operations, the collapse was no longer just economic but transformed into the direct destruction of commercial infrastructure. Central Markets: Major markets in Gaza, Khan Younis, and Rafah sustained extensive damage or complete destruction, resulting in the loss of primary distribution hubs. Retail Shops: In many areas, between 70% and 80% of commercial shops were destroyed or shut down. Entire commercial neighborhoods that once served as main centers of economic activity completely vanished. The Monetary System: The market faced a severe liquidity crisis due to the significant halt or disruption of banking operations, leading to near-total reliance on limited cash or, in some instances, bartering goods. Fourth: War Economy… The Parallel Market With the collapse of the formal market, an alternative economy forced itself onto reality. The Rise of Middlemen: Brokers and middlemen gained control over the movement and distribution of goods, resulting in major price disparities from one area to another. Monopoly and Scarcity: Certain essential commodities were hoarded and resold at exorbitant prices amid the absence of effective regulatory oversight, turning some materials into tools of influence rather than consumer goods. Market Transformation: The market was no longer subject to the logic of supply and demand alone, but rather to the logic of access, control, and the capability to transport and store. Fifth: Economic Losses of the Commercial Sector Despite the difficulty of accessing precise figures due to the ongoing war, estimates indicate the following: Private sector losses in Gaza are estimated at between $15 billion and $20 billion up to the year 2025. Trade and services account for approximately 40% of total direct economic losses. Losses during the initial months of the war ranged between $1.2 billion and $1.8 billion. Data also indicates the destruction of a major portion of commercial capital, whether through the loss of inventory or the complete cessation of activity. Sixth: Impact of the Collapse on Society Families: Thousands of families lost their ability to secure food regularly and shifted to near-total dependency on humanitarian aid, with consumption dropping to the bare minimum. Traders: The sector witnessed widespread bankruptcy among small-scale merchants, with the complete loss of inventory and capital, and a near-total halt in commercial activity. The General Economy: The internal economic cycle stopped, the natural circulation of money ceased, and the economy shifted from being productive and commercial to an relief-based economy dependent on aid. Seventh: 2025–2026… A Near-Stagnant Economy With the war continuing, the commercial sector entered a state of severe contraction: More than 80% of commercial establishments are completely or partially non-operational. A major decline in the middle commercial class. Near-total reliance on humanitarian aid. Absence of an organized market system. Conclusion: A Market Without a Lifecycle Gaza's commercial sector is no longer merely a damaged sector; it has become a near-collapsed economic structure. The natural relationship between production, import, distribution, and consumption no longer exists, replaced instead by a fragile system governed by scarcity and disruption. Under this reality, trade has transformed from an economic activity into a space for daily survival, while the market remains a witness to one of the deepest economic transformations imposed by the war on Gaza since 2023..
.png)
Gaza's Energy Sector: How an Entire City Was Plunged into Darkness
When the evening of October 7, 2023, arrived, residents of the Gaza Strip did not realize that one of the longest periods of darkness in modern Palestinian history had just begun. Within a few days, the energy system—which had already been suffering from chronic crises for years—collapsed, plunging Gaza into an unprecedented phase of near-total power outages, turning fuel into a scarce commodity, and making energy the epicenter of a humanitarian, economic, and health crisis that extended to every home, institution, and hospital. The destruction of the energy sector was not merely a technical or economic loss; rather, it dealt a direct blow to the foundations of civil life in the Strip, where all vital sectors rely on electricity: water, sanitation, hospitals, communications, education, as well as industrial and food production. --- First: The Reality of Energy in Gaza Before the War Prior to October 2023, the Gaza Strip was already suffering from a chronic electricity deficit. The Strip's daily requirements ranged between $500$ and $600\text{ MW}$, while the actual available supply did not exceed $220\text{ MW}$ under the best circumstances. **The primary sources of electricity were:** * **The Gaza Power Plant:** * Established in 2002. * Original design capacity: approximately $140\text{ MW}$. * Relied entirely on imported industrial fuel. * **Israeli Feeder Lines:** * 10 main supply lines. * A total capacity of nearly $120\text{ MW}$. * **Egyptian Lines:** * Capacity ranging between $15$ and $20\text{ MW}$. * Served parts of the southern Gaza Strip. Despite these sources, residents lived under a daily rationing system that involved 8 to 12 hours of power outages even before the war. Second: The Early Days of the War.. The Onset of Collapse Between October 7 and 11, 2023, the energy system suffered its first major shock. The Israeli authorities announced the cessation of electricity and fuel supplies to Gaza, and the feeder lines gradually stopped operating. On October 11, 2023, the Palestinian Energy Authority announced the total shutdown of the sole power plant after its fuel reserves were completely depleted. **From that moment onward:** * Electricity was cut off across the vast majority of the Strip. * Hospitals became entirely dependent on emergency generators. * Thousands of economic facilities ceased operations. * Gaza entered a phase of "complete reliance on limited humanitarian fuel". Third: The Destruction of the Electrical Grid The crisis was not confined to fuel shortages; the grid itself sustained extensive destruction. By the end of 2024, assessment teams indicated that the majority of the electrical infrastructure had been destroyed or severely damaged. Key Documented Damages: * **Transmission and Distribution Networks:** * 🔴 Destruction of more than 3,080 kilometers of electricity lines. * 🔴 Damage to thousands of electrical poles. * 🔴 Extensive destruction of underground cables. * 🔴 Dozens of transformer stations rendered out of service. * **Electrical Transformers:** * 🔴 Destruction or damage of approximately: * 1,980 overhead transformers. * 125 ground transformers. * **Operational Facilities:** * 🔴 Severe damage to: * Control centers. * The electricity company’s warehouses. * Maintenance workshops. * The technical vehicle fleet. Fourth: Direct Financial Losses According to technical studies issued by experts from the Electricity Distribution Company, the financial losses are detailed as follows: | Item | Loss Value | | --- | --- | | **Damage to Networks and Facilities** | $259.85 million | | **Loss of Revenue** | $212.3 million | | **Total Direct Losses** | **$472.15 million** | However, these figures do not include: * National economic losses. * Indirect damages. * Full reconstruction costs. Consequently, more recent estimates indicate that the bill for the electricity sector alone may exceed **$700 million** once the assessment is fully completed. Fifth: The Fuel Crisis If the destruction of the grid represents one side of the crisis, the fuel shortage is the other. Since October 2023 and up to the present day: * Fuel supplies have faced recurrent interruptions. * Entering quantities have been subjected to severe restrictions. * Priority has been strictly given to hospitals and water plants. **This crisis has led to:** * **Hospitals:** Scaling back surgical operations, shutting down certain departments, and threatening the functionality of intensive care units. * **Water:** A decline in the production of desalinated water, the shutdown of numerous wells, and a reduction in water pumping to households. * **Communications:** Recurrent disruptions to telephone and internet services, and the halting of numerous transmission stations. Sixth: Solar Energy.. The Last Resort Before the war, thousands of homes and institutions relied partially on solar energy. However, the war resulted in: * 🔴 The destruction of a large number of solar panels. * 🔴 The theft or loss of batteries due to displacement and widespread destruction. * 🔴 System failures due to the total absence of maintenance. Despite this, solar energy remained one of the most critical, yet limited, sources of electricity available to the population during the war years. Seventh: The Impact of Energy Collapse on the Health Sector The health sector serves as the clearest example of the gravity of the electricity collapse. Modern hospitals rely on electricity for: * Operating rooms. * Mechanical ventilators. * X-ray and imaging machines. * Laboratories. * Incubators for premature babies. * Kidney dialysis units. During the war, generators turned into a lifeline, while fuel became a decisive factor in keeping hospitals operational. Eighth: Impact of the Crisis on Water and Sanitation Before the war, desalination and wastewater treatment plants consumed a significant portion of the electricity generated in Gaza. With the collapse of energy: * Numerous stations shut down completely. * The production of clean water declined sharply. * Environmental pollution risks escalated significantly. * Quantities of untreated sewage flowed directly into the sea. Consequently, securing water became one of the most prominent daily challenges for the population. Ninth: The Economy in the Dark The energy crisis cannot be separated from the broader economic collapse. Electricity serves as the primary engine for all economic activity. With its collapse: * 📌 Factories shut down. * 📌 Production workshops were disrupted. * 📌 Food industries suffered severe declines. * 📌 Cold chains completely collapsed. * 📌 Production costs soared at unprecedented rates. Operating a private generator for just a few hours a day became a financial burden that exceeded the capacity of most enterprises. Tenth: Reconstruction and Future Challenges According to estimates by the World Bank, the United Nations, and the European Union, Gaza requires more than **$53 billion** for reconstruction and recovery. The energy sector will be one of the most costly and complex sectors due to the following reasons: * Widespread destruction of grids. * The need to replace thousands of transformers. * Rehabilitating the sole power plant. * Upgrading transmission and distribution systems. * Introducing large-scale renewable energy solutions. Energy experts believe that rebuilding the electrical system could take many years, even if full funding is secured. More than two and a half years after the outbreak of the war, the electricity crisis in Gaza is no longer just a service disruption; it has become one of the defining features of the war itself. Behind every number related to energy lies the story of a hospital fighting to survive, a water well that ceased to function, a factory that shut its doors, or a family that spent endless nights in total darkness. Electricity in Gaza has transformed from a public utility into an element of sheer survival. The collapse of the energy sector stands as one of the most stark indicators of the scale of destruction inflicted upon the Strip since October 7, 2023, in a war that has reshaped infrastructure, daily life, and the Palestinian economy in an unprecedented manner..
Death Toll in Gaza Strip Rises to 72,991, Injuries to 173,219 Since Onset of Aggression
GAZA, June 11, 2026 – Medical sources in the Gaza Strip announced today, Thursday, that the death toll from the ongoing Israeli occupation aggression on the Strip has risen to 72,991 fatalities and 173,219 injuries since the outbreak of the aggression on October 7, 2023. The sources reported that hospitals across the Gaza Strip received 7 injuries over the past 24 hours. They further noted that the total number of fatalities since the ceasefire took effect on October 11 of last year has risen to 981, while total injuries reached 3,111, with 783 bodies recovered during this period. The sources pointed out that a number of victims remain trapped under the rubble and on the roads, as ambulance and rescue crews are still unable to reach them up to this moment..

An Economy Under Siege: The West Bank and East Jerusalem Between Income Loss, Mobility Paralysis, and the Clearance Revenues Crisis Since October 7, 2023
Gaza: The Living Memory Since October 7, 2023, the Palestinian economy in the West Bank and East Jerusalem has entered an unprecedented phase of economic contraction. This is the result of three overlapping major shocks: the loss of the labor market inside Israel, the tightening of movement restrictions within the West Bank, and the escalating financial crisis of the Palestinian Authority (PA) due to the withholding of clearance revenues. Data issued by the World Bank, the United Nations Conference on Trade and Development (UNCTAD), and the International Labour Organization (ILO) indicate that the Palestinian economy has suffered one of the deepest contractions in its modern history, with protracted effects impacting the labor market, production, consumption, and public finance. ### I. A Historic Economic Contraction Data from the World Bank and UNCTAD indicate that during 2024, the Palestinian economy recorded a contraction of approximately 27%, representing one of the highest rates of decline recorded in the region within a short timeframe. Furthermore, the Gross Domestic Product (GDP) dropped to about 70% of its 2022 level, while per capita income plummeted to levels reminiscent of the early 2000s—amounting to the loss of more than 22 years of economic progress. In the West Bank specifically, contraction estimates ranged between 19% and 23%, driven by declining local consumption, the suspension of a broad segment of investments, and the disruption of internal commercial activity between cities and villages. ### II. The Labor Market: Loss of Tens of Thousands of Jobs Prior to October 7, 2023, approximately 177,000 Palestinian workers from the West Bank were employed inside Israel and the settlements, serving as one of the most vital income sources for the Palestinian economy. Following the outbreak of the war, the number of workers permitted to work dropped to only about 24,000. This signifies a direct loss of approximately 153,000 job opportunities, representing a decline of nearly 86%. World Bank estimates indicate that the Palestinian economy loses approximately $25.5 million daily in workers' income, which translates to about $765 million per month, and roughly $9.3 billion annually in lost wages. This decline has directly impacted household purchasing power, increased debt levels, and weakened demand in local markets, while placing growing pressure on the banking system. ### III. Unemployment: A Deepening Crisis in the Labor Market According to data from the ILO and the Palestinian Central Bureau of Statistics (PCBS), unemployment rates in the West Bank spiked from about 13% prior to the war to a peak of around 35% during the initial months of the crisis, before later stabilizing at levels between 28% and 29% during 2025. Based on estimates of the West Bank labor force size—which stands at nearly 900,000 workers—these percentages translate to between 250,000 and 315,000 unemployed individuals, a level unprecedented in the Palestinian market in recent years. ### IV. Clearance Revenues: The Severest Financial Crisis Clearance revenues—which Israel collects on behalf of the Palestinian Authority—form the backbone of public revenues, accounting for more than 65% of the Palestinian treasury's income. In official statements, the Palestinian Minister of Finance noted that Israel is withholding and deducting a large portion of these clearance revenues, estimating the total frozen and withheld funds at between $4.4 billion and $5 billion. This reflects the magnitude of the compounding financial crisis facing the Palestinian Authority over the last two years. The Ministry of Finance confirms that these deductions have accumulated in recent years, leading to a severe liquidity crisis that has disrupted regular salary payments. Consequently, partial salaries have been paid across multiple periods, alongside an expanded reliance on borrowing from local banks and delaying obligations toward the private sector. Furthermore, estimates from the World Bank and UNCTAD indicate that total Israeli deductions from clearance revenues between 2019 and 2025 range between $1.7 billion and $2.0 billion, rendering the clearance revenues file one of the most dangerous sources of financial pressure on the Palestinian economy. ### V. Checkpoints, Closures, and the Fragmentation of Economic Geography Data from the United Nations Office for the Coordination of Humanitarian Affairs (OCHA) shows that the number of obstacles and checkpoints in the West Bank rose from about 642 in mid-2023 to around 793 in 2024, and reached approximately 925 by 2025—reflecting an increase of nearly 43%. These restrictions have lengthened travel times between Palestinian cities by two to five times, driven up transport and freight costs, disrupted internal supply chains, and transformed the West Bank into semi-isolated economic zones, directly impacting trade and production. ### VI. The Private Sector: Broad Contraction in Economic Activity Economic surveys indicate that approximately 95% of Palestinian businesses recorded a decrease in sales, while 76% reported experiencing transport and distribution issues. Furthermore, nearly 29% of businesses indicated they were forced into partial or full closure during periods of the crisis. This reflects a widespread decline in economic activity resulting from falling demand and deteriorating purchasing power. ### VII. Construction and Agriculture Sectors The construction sector is among the hardest hit due to its heavy reliance on Palestinian workers employed inside Israel. The suspension of workers' entry into Israel has led to partial paralysis in the sector, halting or slowing down thousands of residential projects, alongside falling demand for construction materials and losses estimated at hundreds of millions of dollars. As for the agricultural sector, it has been severely impacted by the denial of access to lands near the separation wall and settlements, alongside a decline in production seasons—particularly the olive harvest in 2023 and 2024. This is compounded by difficulties in marketing and transport, leading to accumulated losses in farmers' incomes. ### VIII. Military Incursions and Indirect Economic Impacts Frequent military incursions into West Bank cities and camps have led to recurring market closures and the disruption of educational and economic institutions for hours or days. Additionally, damage to infrastructure—including roads, water, electricity, and telecommunications—has caused daily indirect operational losses. While these are difficult to quantify precisely, they recur systematically across several areas. ### IX. East Jerusalem: An Economy Under Pressure East Jerusalem has witnessed a marked decline in economic activity, particularly within the domestic and religious tourism sectors. Market activity in the Old City has dropped, alongside the closure or downscaling of hundreds of commercial establishments, and a decline in the performance of the hotel and restaurant sectors due to diminished traffic arriving from the West Bank. --- The aggregate economic data indicates that since October 7, 2023, the Palestinian economy in the West Bank and East Jerusalem has entered a phase of deep and interconnected contraction. The loss of tens of thousands of jobs has coincided with a severe liquidity crisis caused by the withholding of clearance revenues, alongside the restriction of internal movement via checkpoints and closures. According to the World Bank, the continuation of these conditions could entrench a state of long-term economic stagnation that will be difficult to reverse, even in the event of subsequent political or security improvements. This makes the current crisis one of the most dangerous economic shifts the Palestinian economy has witnessed in its modern history..
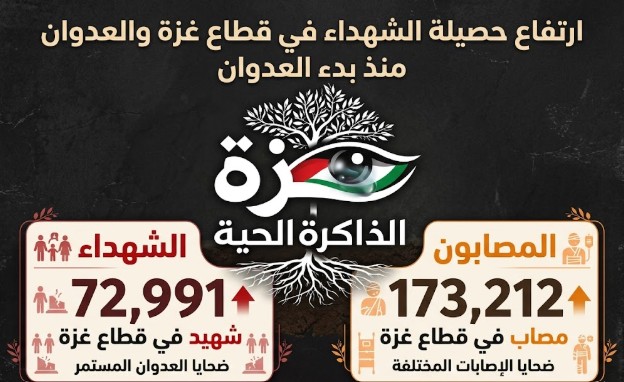
Death toll in Gaza strip rises to 72,991, with injuries reaching 173,212 since the beginning of the aggression
GAZA, June 10, 2026 – Medical sources in the Gaza Strip announced today, Wednesday, that the death toll from the ongoing Israeli occupation aggression on the Strip has risen to 72,991 martyrs, and 173,212 injuries, since the start of the aggression on October 7, 2023. The sources reported that hospitals in the Gaza Strip received 3 martyrs and 5 injuries over the past 24 hours. They pointed out that the total number of martyrs since the ceasefire on October 11 last year has risen to 981, and total injuries to 3,104, while 783 bodies have been recovered. The sources further indicated that a number of victims remain under the rubble and on the roads, as ambulance and rescue crews are still unable to reach them up to this moment..
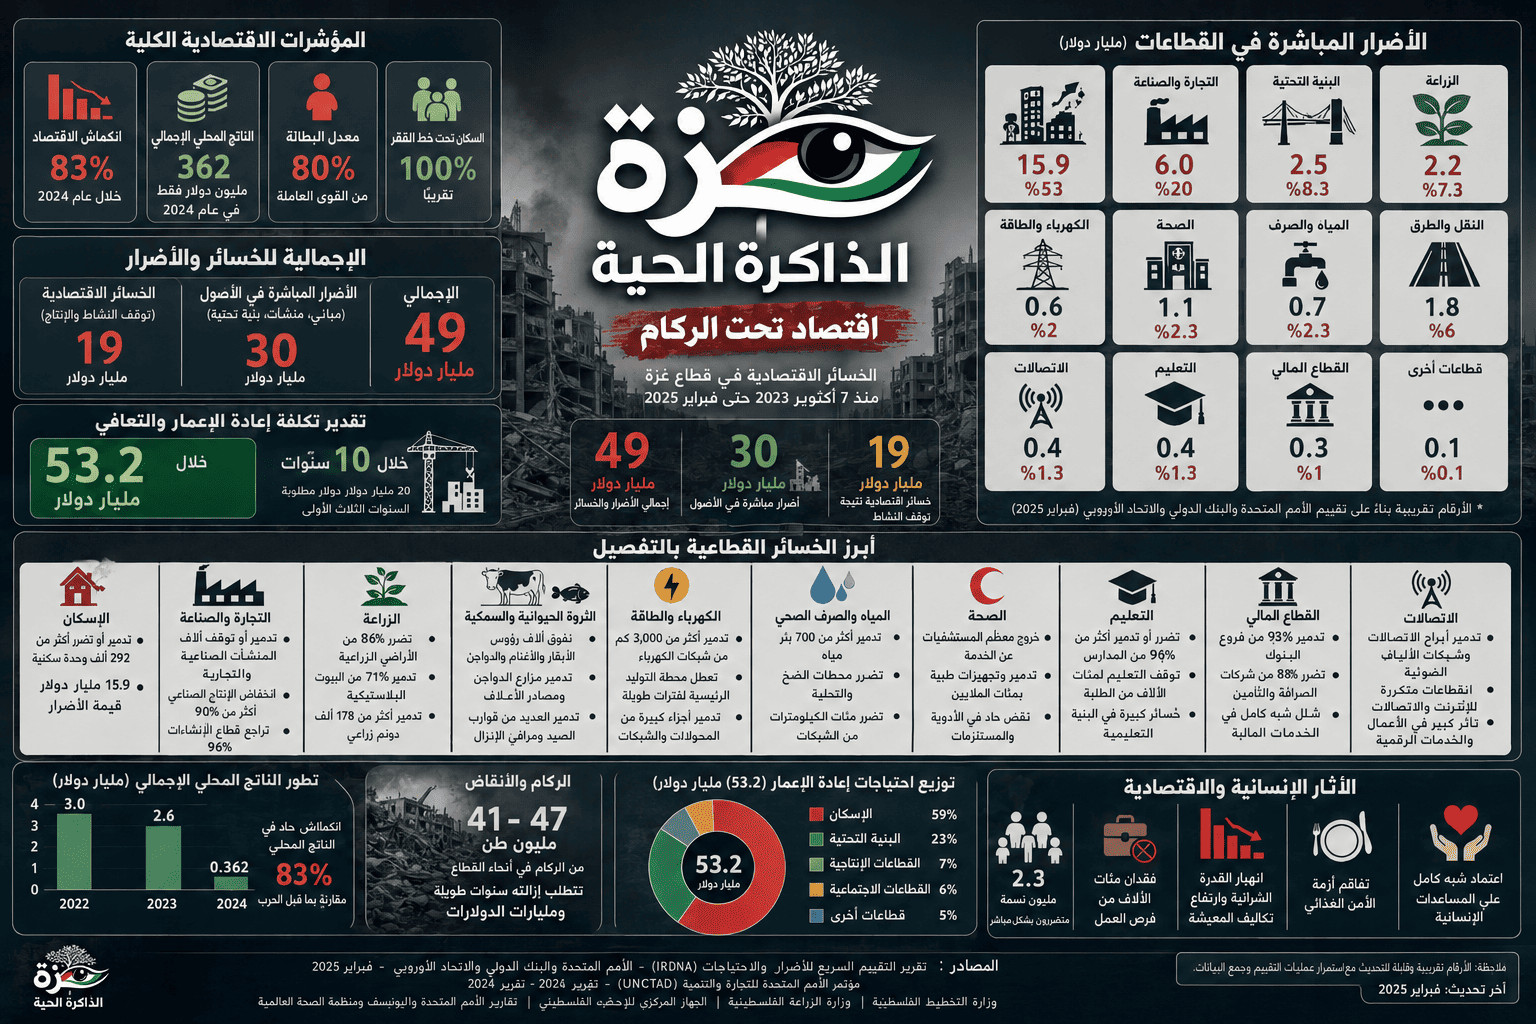
From a Blockaded Economy to an Economy Under the Rubble: The Economic Losses in the Gaza Strip Since October 7, 2023
Gaza Al-Thakira Al-Hayya (The Living Memory) – June 9, 2026 – When the war on the Gaza Strip broke out on October 7, 2023, the destruction was not confined to residential buildings or civilian facilities; rather, it extended to obliterate the entire economic infrastructure. Within a few months, the Strip’s economy suffered an unprecedented blow, prompting international institutions to describe what transpired as one of the largest economic collapses the world has witnessed in a geographically limited area during modern history. Gaza, which spans an area of approximately 365 square kilometers and is home to more than 2.3 million people, was already suffering from the effects of a continuous blockade imposed since 2007, an unemployment rate exceeding 45% prior to the war, and a fragile economy heavily reliant on humanitarian aid. With the outbreak of the war, most economic, productive, and service sectors collapsed, and the infrastructure sustained widespread destruction. According to a joint assessment issued by the United Nations, the World Bank, and the European Union in February 2025, the value of direct damages reached approximately $30 billion, while economic losses resulting from the cessation of productive and service activities amounted to around $19 billion, bringing the total damages and losses to nearly $49 billion during the first year of the war alone. Chapter I: An Economy Stripped of Its Vital Capacity Prior to the war, the annual Gross Domestic Product (GDP) of the Gaza Strip stood at approximately $3 billion, despite the blockade and restrictions imposed on movement and trade. However, during 2024, the Gazan economy recorded the largest collapse in its modern history. Data from the United Nations Conference on Trade and Development (UNCTAD) indicates that Gaza's economy contracted by 83% during 2024, while the GDP plummeted to a mere $362 million. This collapse signifies that most economic activities ceased or vanished, leaving thousands of establishments unable to operate or produce. Furthermore, unemployment surged to nearly 80% of the workforce, rendering the majority of the Strip's population dependent on humanitarian and food assistance. United Nations estimates indicate that the war erased nearly seven decades of human and economic development progress in Gaza. Chapter II: Housing and Real Estate... The Destruction of Accumulated Wealth The housing sector stands as the single most affected sector by the war. Real estate in Gaza was not merely shelter; it represented a repository of wealth and the life savings of Palestinian families who invested long years into building their homes, apartments, and properties. According to the World Bank assessment: The value of damages in the housing sector reached approximately $15.9 billion. The residential sector accounted for 53% of the total recorded damages. More than 292,000 housing units were damaged or destroyed. Entire neighborhoods were damaged in Gaza City, Jabalia, Beit Hanoun, Beit Lahia, Khan Younis, and Rafah. UN estimates indicate that more than 70% of the buildings in the Strip sustained varying degrees of destruction or damage. These losses did not only trigger a housing crisis but also led to the collapse of a massive portion of the real estate and construction market, resulting in the loss of tens of thousands of jobs tied to this sector. Chapter III: Trade and Industry... Halting the Engines of Production Before the war, thousands of industrial and commercial establishments formed the backbone of the Gazan economy. Gaza encompassed: Food processing factories. Garment and textile factories. Furniture factories. Plastic industries. Metal industries. Small handicraft workshops. However, the war resulted in: The destruction or closure of thousands of establishments. The destruction of warehouses containing goods and raw materials. A near-total cessation of industrial production. According to international institutional estimates: Industrial production dropped by more than 90%. Construction sector activity plummeted by 96%. The trade and industry sector accounted for roughly 20% of total direct damages. Consequently, this led to the loss of tens of thousands of job opportunities and the collapse of local productive capacity. Chapter IV: Agriculture... The Loss of Land and Food Sources Prior to the war, the agricultural sector constituted a fundamental pillar of the local economy. It contributed nearly 10% to the GDP and provided direct and indirect income for hundreds of thousands of citizens. However, satellite imagery and UN reports revealed a staggering scale of destruction. By 2025: Approximately 86% of agricultural lands were damaged. Only 1.5% of agricultural land remained safely usable. 71% of greenhouses were damaged. More than 80% of agricultural wells were damaged. Estimates from the Palestinian Ministry of Agriculture indicate: The destruction of over 178,000 agricultural dunams. The destruction of nearly 1,000 agricultural wells. The destruction of hundreds of cattle, sheep, and poultry farms. As a result, thousands of farmers lost their sole source of income. Chapter V: Livestock and Fisheries The livestock sector suffered severe losses due to the destruction of farms and the perishing of animals from bombardment and feed shortages. The losses encompass: Thousands of head of cattle. Tens of thousands of sheep and goats. Millions of poultry. Egg and milk production farms. Meanwhile, the marine fishing sector dealt a heavy blow: The destruction of a large number of fishing boats. Damage to ports and fishermen’s harbors. The complete idleness of thousands of fishermen. This sector had previously provided direct and indirect income to approximately 100,000 people prior to the war. Chapter VI: Electricity and Energy Electricity represents the lifeblood of a modern economy, yet this sector suffered comprehensive devastation. Official Palestinian estimates point to: The destruction of thousands of meters of electrical grids. The destruction or damage of major transformers. The prolonged disruption of the sole power plant. Additionally, over 3,000 kilometers of electrical networks were destroyed. This catastrophic failure led to: The idling of factories. The disruption of hospitals. A decline in agricultural production. The collapse of water and telecommunication services. Chapter VII: Water and Sanitation Even before the war, Gaza suffered from a chronic water crisis. However, the war exacerbated the situation to an unprecedented degree. Estimates indicate: The destruction of more than 700 water wells. Damage to pumping stations. The destruction of vast sections of water networks. Damage to desalination plants. Furthermore, hundreds of kilometers of sewage networks were damaged, leading to a severe decline in water supplies and escalating environmental and health hazards. Chapter VIII: The Healthcare Sector The health sector constituted one of the most heavily targeted sectors during the war. According to United Nations estimates: The majority of hospitals sustained severe damage. A large number of hospitals were knocked entirely or partially out of service. Dozens of health centers and clinics were damaged. The sector also lost: Advanced medical equipment. Laboratories. Ambulances. Pharmaceutical warehouses. Total losses are estimated in the hundreds of millions of dollars. Chapter IX: Education... The Loss of Human Capital Prior to the war, Gaza possessed: Hundreds of public and private schools. Universities, colleges, and institutes. However, the war resulted in: The destruction or damage of the vast majority of educational institutions. The suspension of education for extended periods. Stripping hundreds of thousands of students of their right to education. UN estimates indicate that more than 90% of educational buildings sustained destruction or damage. The loss here is not confined to physical structures; it encompasses the loss of entire academic years and long-term consequences for human capital. Chapter X: Roads and Transportation The road network suffered catastrophic damage. Losses include: The destruction of hundreds of kilometers of roads. The destruction of bridges and internal crossings. Damage to transport networks and logistics services. This extensive damage severely hindered the movement of goods, commodities, relief aid, and rescue operations. Chapter XI: Telecommunications and Information Technology Before the war, the telecommunications sector was one of the few sectors exhibiting relative growth. However, the war led to: The destruction of telecom towers. The obliteration of fiber-optic networks. Recurrent blackouts of internet and phone services. Software development companies and digital service providers, which previously provided employment opportunities for the youth, were also severely impacted. Chapter XII: Banking and Financial Services The Palestinian financial system in Gaza sustained unprecedented losses. According to World Bank estimates: Approximately 93% of bank branches were destroyed. 88% of exchange companies were damaged. 88% of insurance companies were damaged. Only a very limited number of Automated Teller Machines (ATMs) remained operational. This led to: Extreme difficulty in accessing funds. The paralysis of commercial transactions. A sharp contraction in banking activity. Chapter XIII: The Labor Market The number of employed individuals in Gaza before the war was close to 500,000 workers, both directly and indirectly. However, the war caused: The loss of hundreds of thousands of jobs. The collapse of entire sectors of employment. A surge in unemployment to roughly 80%. Consequently, the vast majority of families lost their primary sources of income. Chapter XIV: Municipalities and Public Services Municipalities suffered extensive losses that included: Heavy machinery and equipment. Administrative buildings. Road networks. Sanitation and waste management services. This severely crippled the capacity of local government units to deliver essential public services. Chapter XV: Rubble... The Other Face of Losses One of the most telling images reflecting the magnitude of the catastrophe is the mountains of rubble strewn across various parts of the Strip. United Nations estimates point to the existence of between 41 and 47 million tons of debris. This rubble represents: Destroyed homes. Demolished factories. Schools and hospitals. Entire flattened infrastructure networks. The mere removal of this rubble will require years of labor and billions of dollars. Chapter XVI: The Cost of Reconstruction According to the joint assessment of the United Nations, the World Bank, and the European Union: $53.2 billion is required for reconstruction and recovery needs spanning a ten-year period. $20 billion is urgently required within the first three years. Housing and infrastructure comprise the lion's share of this cost. As destruction persisted through 2025 and into 2026, international estimates suggest that the reconstruction bill will climb to significantly higher levels. How Gaza's Economy Was Erased Gaza has not witnessed an economic loss of this magnitude since the beginning of the occupation in 1967. In less than two years, the housing, agriculture, manufacturing, trade, services, and infrastructure sectors collapsed entirely; GDP contracted by 83%, unemployment soared to unprecedented levels, and vast expanses of cities and refugee camps were reduced to ruins. Numbers alone do not capture the true scale of the catastrophe. Behind every destroyed home is a family that lost its life savings; behind every halted factory are workers who lost their livelihoods; and behind every ruined school or university is an entire generation whose educational opportunities have been disrupted. The economic losses in Gaza are not merely figures in billions of dollars; they tell the story of an entire society whose economic and social foundations have been decimated, in one of the greatest economic and humanitarian disasters of the twenty-first century..